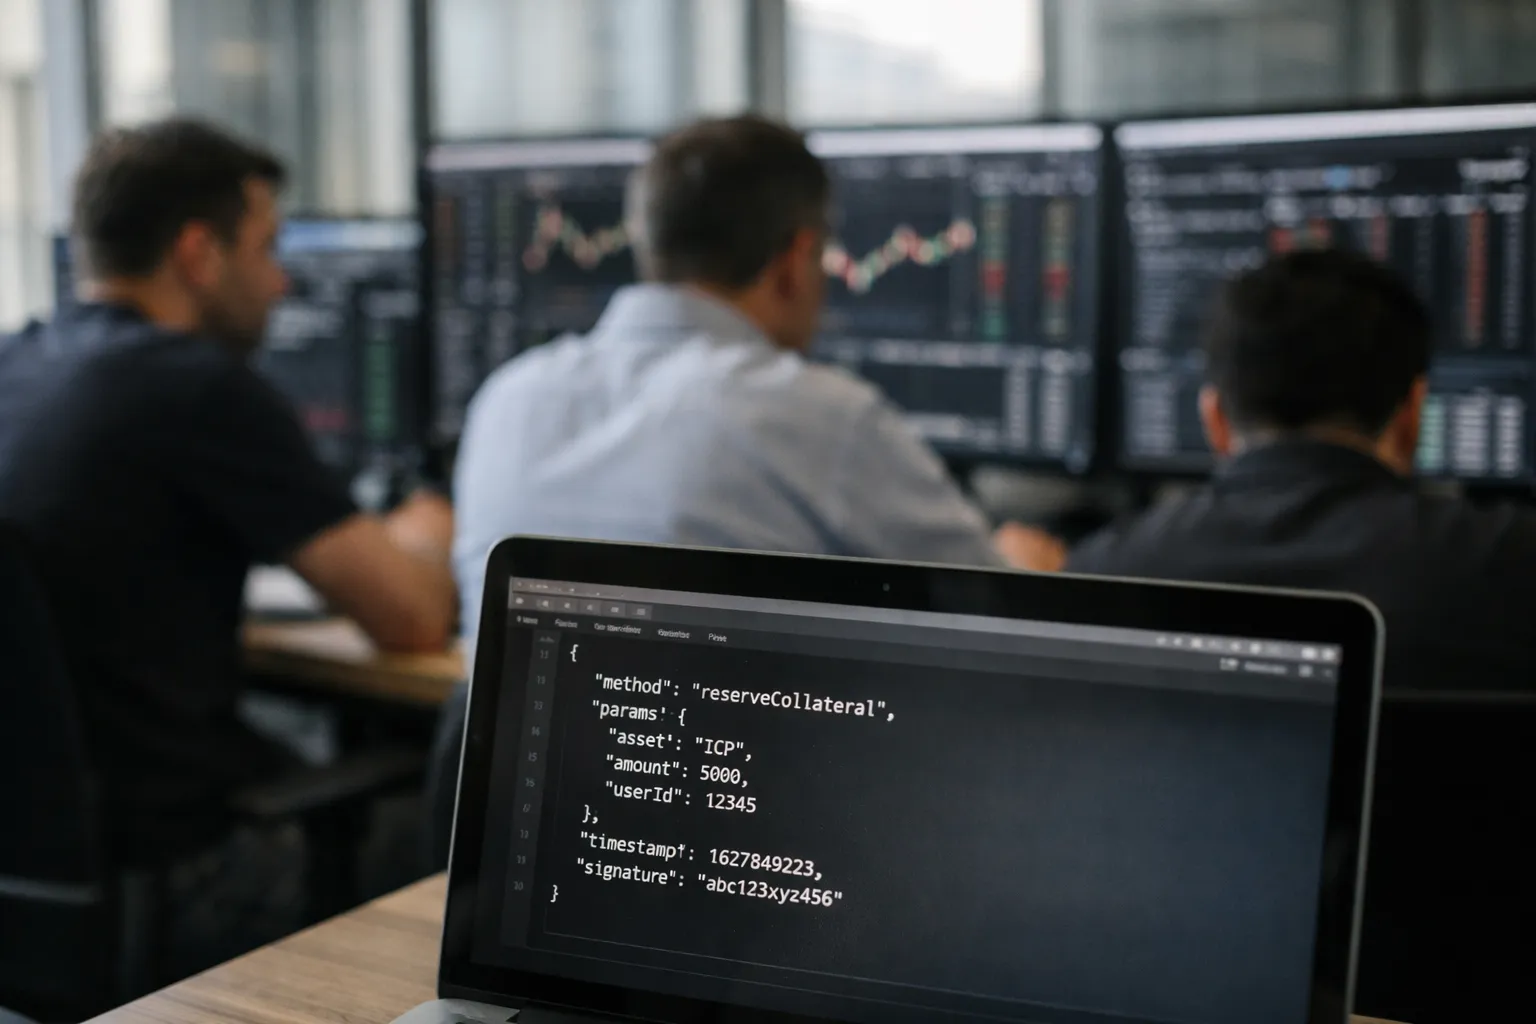
An industry consortium of exchanges, custodians and institutional trading firms today unveiled a new protocol to enable permissioned, cross‑exchange collateral pooling for crypto margin accounts. The initiative — dubbed the Interchangeable Collateral Protocol (ICP) in the consortium statement — aims to let institutional traders use a single pooled collateral balance to support positions on multiple venues without duplicating asset holdings.
What the protocol does
At a technical level the ICP standardizes APIs and token formats for representing custody‑backed collateral (tokenized custody receipts), a permissioning layer that enforces counterparty and jurisdictional rules, and an atomic settlement primitive so margin transfers and liquidations can occur across participants without transient credit exposure.
According to the consortium, the protocol allows a verified institutional account to nominate a custodial wallet as a shared collateral pool. Participating exchanges can then reserve, lock and claim portions of that pool via the standardized API — subject to pre‑agreed rules and custodial controls — rather than requiring the trader to maintain segregated collateral on each venue.
Why traders care
- Capital efficiency: Institutions frequently duplicate stablecoins or BTC across exchanges to meet margin and collateral requirements. Pooling collateral can reduce locked capital and free assets for trading or borrowing.
- Simpler cross‑venue hedges: Traders executing multi‑venue strategies (e.g., perpetuals vs. options across different exchanges) can rebalance positions faster without on‑chain transfers or off‑exchange internal transfers.
- Operational reduction: Fewer transfers reduce settlement friction and on‑chain fees, and the standardized API aims to simplify reconciliation and reporting.
How it works in practice
The protocol operates in three layers:
- Tokenized custody receipts: Custodians issue permissioned tokens that represent custody of base assets (USDC, BTC, ETH, tokenized cash equivalents). These receipts are not public tokens; they include cryptographic proofs and metadata required by the protocol.
- Permissioning and legal rails: Access controls and KYC/AML constraints are encoded in the protocol’s permissioning layer so exchanges only accept collateral from approved custodians and accounts.
- Atomic reservation and settlement: Exchanges can atomically reserve collateral for margin calls and execute cross‑participant liquidation operations through the protocol’s settlement primitives, minimizing temporary unsecured exposure.
In a press note, the consortium emphasized that ICP is not a public blockchain or a replacement for custody; it is an interoperability standard that sits on top of existing custody and exchange infrastructure and uses cryptographic proofs and off‑chain verification to effect trust boundaries.
Participants and governance
The founding group includes institutional custody providers, several regulated exchanges and multiple market‑making desks. The consortium says it will open the specification to industry review and invite other exchanges and custodians to join. Governance will be handled by a multi‑stakeholder council with representation from custodial institutions, regulated exchanges and buy‑side members.
Early participants described the protocol as a pragmatic compromise between fully on‑chain margining and the status quo of duplicated off‑exchange collateral.
Risks and open questions
Traders and risk managers should weigh several operational and legal considerations.
- Counterparty concentration: Pooling collateral concentrates short‑term counterparty exposure if multiple venues draw on the same pool simultaneously during stressed markets.
- Jurisdictional complexity: Permissioning has to reconcile different regulatory regimes (for example, local custody rules, sanctions screening and insolvency law) which may limit which custodians or exchanges can participate for certain clients.
- Liquidity and speed: The protocol’s benefits hinge on fast, atomic settlement. Any latency or failures in the settlement layer could impede liquidations and increase systemic stress.
- Regulatory scrutiny: Regulators may view pooled collateral models through the lens of custody rules, customer asset segregation, or broker‑dealer capital requirements. Clear legal frameworks will be critical before widespread adoption.
Market impact and next steps
Industry analysts and trading heads told Crypto Trading Pro they expect the ICP to be adopted first by large, regulated institutional desks with multi‑venue access — particularly those running delta‑neutral or cross‑venue arbitrage strategies where collateral duplication is a material drag on returns.
In pilot tests cited by participating firms, initial implementations reportedly reduced collateral duplication by an estimated 15–30% for participating accounts, though those figures are preliminary and depend on strategy profile and risk limits.
The consortium plans a phased roll‑out: a closed pilot with select institutional clients in Q3 2026, an expanded pilot across additional exchanges through Q4, and a public specification release with open API documentation thereafter. Integration timelines will vary by custodian and exchange, with some participants signaling support for the protocol’s minimum feature set already this quarter.
What traders should do now
- Talk to prime brokers and custodians about whether they plan to support ICP and the expected integration timelines.
- Assess strategies that currently suffer from collateral duplication — cross‑venue delta hedges, basis trades and liquidity provision — to quantify potential capital savings.
- Clarify legal implications with counsel, including custody arrangements and insolvency protections for pooled collateral.
For active traders, cross‑exchange collateral pooling could lower capital friction for multi‑venue strategies and speed execution. But meaningful adoption will require robust legal frameworks, fail‑safe settlement mechanics and careful risk governance — areas the consortium has flagged as priorities for the coming quarters.