As liquidity migrated on‑chain and to Layer‑2s during 2024–2026, a new, measurable form of microstructural risk has emerged for market makers and active traders: orderflow toxicity driven by mempool visibility, sequencer behavior and builder networks. This article offers a focused, actionable framework for measuring that toxicity, shows which signals matter in practice, and recommends tactics to limit adverse selection when quoting or executing in on‑chain orderbooks and DEX AMMs.
Why toxicity matters now
Orderflow toxicity—adverse selection that turns seemingly profitable market‑making into losses—has always existed. What changed is the visibility and speed of order information: public and private mempools, builder networks, and permissioned sequencers create information asymmetries between liquidity providers (LPs) and searchers. Combined with rapid sequencer innovations across major L2s, these factors distort execution quality, increase sandwich and reorg risks, and raise the realized spread LPs must earn to break even.
For traders and LPs, the practical consequence is simple: quoted spreads and fill strategies that worked in 2022–23 now systematically underprice the true cost of providing liquidity on many venues.
A practical measurement framework
To manage toxicity you first need to measure it. Below are concrete metrics, data sources and calculation methods you can implement with standard on‑chain and mempool feeds.
Core metrics
-
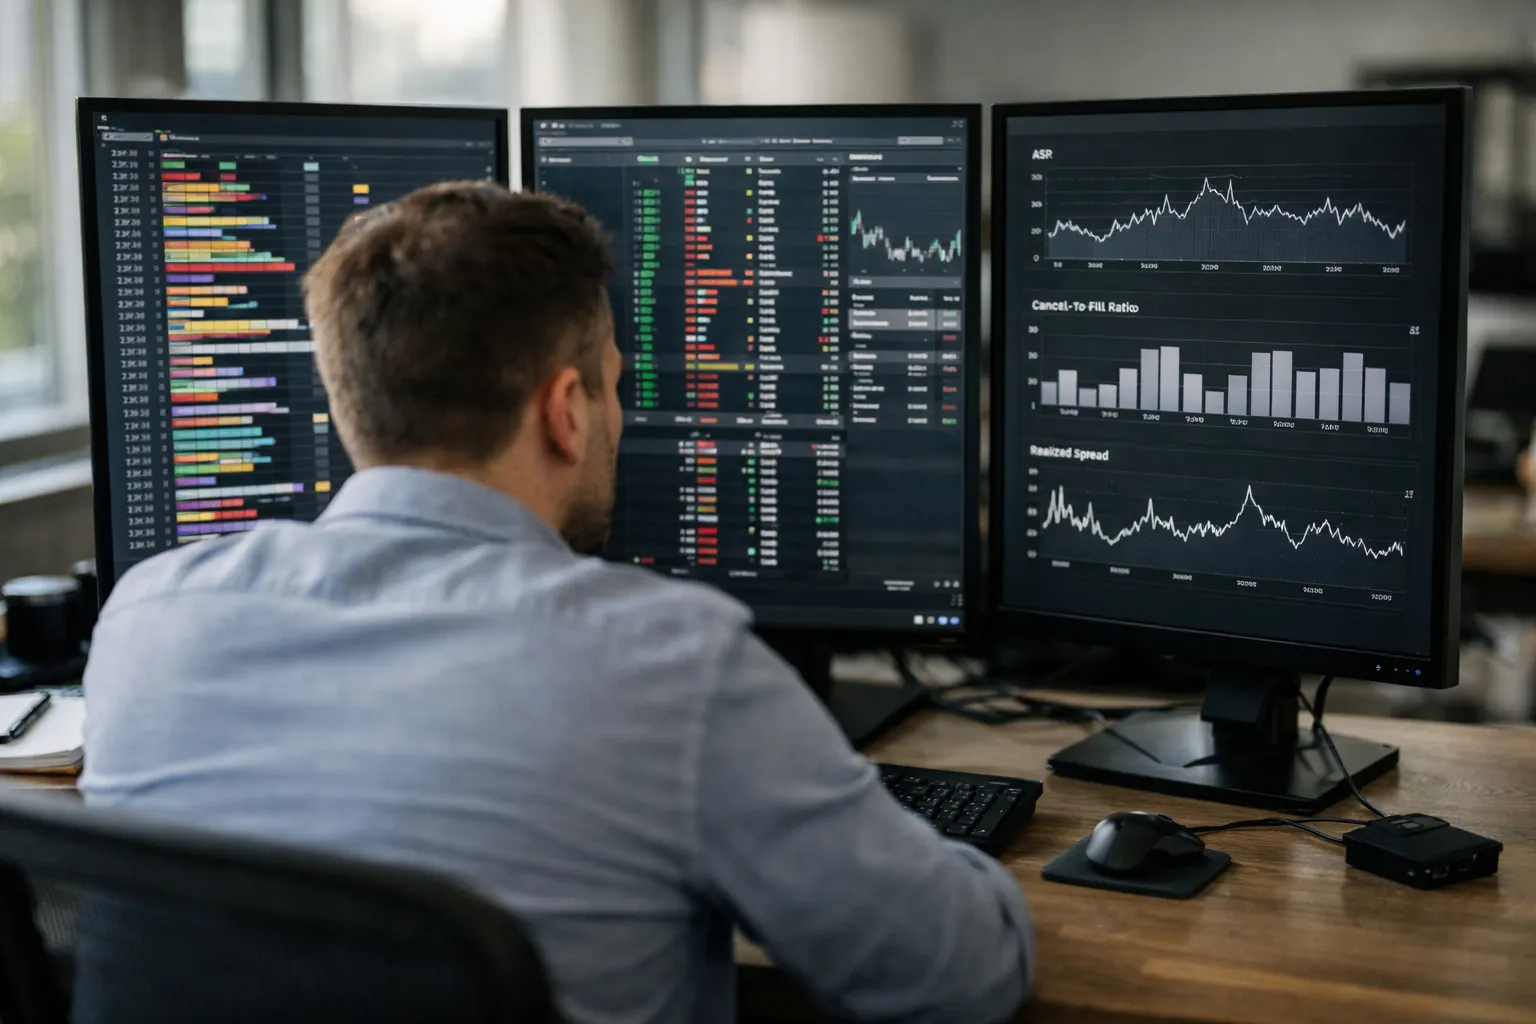
Adverse Selection Rate (ASR) — percentage of fills that move unfavorably by X ticks within T seconds. Compute per instrument:
- Record each fill (price, side, timestamp).
- Define X (e.g., 0.1% price move) and T (e.g., 5s for fast markets, 60s for slower markets).
- ASR = fills where subsequent midprice moves against the fill ≥ X within T / total fills.
- Realized Spread vs. Quoted Spread — realized spread = (execution midprice change over T) minus quoted spread at fill. Persistent negative gap implies toxicity.
- Cancel‑to‑Fill Ratio — cancellations preceding large trade clusters indicate predatory searcher behavior. High ratios correlated with sandwich attacks and searcher probing.
- Immediate Fill Slippage — difference between expected fill price (best quote when order posted) and actual fill; split by maker/taker identity where possible.
- Mempool Lead Time — average latency between a transaction appearing in a public mempool and its inclusion by a builder/sequencer; short public lead times with large builder activity signals high extraction risk.
Data sources and practical setup
- On‑chain trade logs and event traces from node providers (e.g., Alchemy, Infura) or indexers for fills and cancellations.
- Mempool watchers and builder‑network feeds (Flashbots’ public telemetry, public mempool streams, private relay telemetry where accessible).
- Market data providers (Coin Metrics, Kaiko, Nansen) and CLOB APIs (dYdX, centralised exchange REST/WebSocket) to correlate off‑chain and on‑chain activity.
- Simple ETL: persist fills, cancellations, mempool timestamps and sequencer inclusion times into a time‑series DB and compute rolling metrics (1h, 24h, 7d windows).
Interpreting the signals — what each metric means
Metrics are not isolated. Combine them for a clearer readout:
- High ASR + negative realized spread: active adverse selection by liquidity takers or searchers. Reduce posted size and widen spreads.
- High cancel‑to‑fill with low public mempool lead: searchers probe privately; expect sandwich and extractive blocks.
- Low mempool lead time but stable realized spreads: builder competition is robust but not necessarily extractive—may reflect fair sequencing auctions or transparent block builders.
- Correlation spikes around protocol events: token listings, airdrops, or L2 sequencer reconfigs often cause temporary toxicity surges; automatically raise guardrails during these windows.
Case studies and examples (illustrative)
Below are stylized, realistic examples of how these metrics flagged issues and guided tactical decisions.
- Stablecoin pool on an L2: An LP noticed ASR rose to 22% for USDX trading between 12:00–14:00 UTC across several days, with cancel‑to‑fill ratios spiking 3x. Investigation of mempool feeds showed private relay submissions clustered just before block inclusion. The LP cut posted sizes by 50% and switched to maker‑protected order types; realized losses dropped to break‑even within 48 hours.
- High‑volatility token listing: On token listing day a CLOB on an L2 experienced a sudden drop in mempool lead time and a doubling of immediate fill slippage. Traders who disabled aggressive taker strategies and used RFQ/OTC for large exposure avoided 1–2% execution cost that others paid.
Tactical playbook for traders and LPs
Translate measurements into behavior. Below are practical, prioritized tactics.
For market makers / LPs
- Implement adaptive quoting: tie quoted spreads and posted sizes to rolling ASR and realized spread metrics. Example rule: if ASR > 15% or realized spread 0 for 24h, widen spread by X bps and reduce size by Y%.
- Use post‑only and maker‑protected orders where supported to avoid unintended taker executions.
- Prefer venues with explicit anti‑MEV protections or transparent sequencer auctions. If sequencing is opaque, increase the premium on quoted spreads.
- Split risk across venues with orthogonal sequencer architectures to avoid a single point of extraction risk.
For takers / execution traders
- Monitor toxicity before slicing: if ASR and mempool volatility are high, shift large trades to RFQ, dark pools, or time‑weighted slicing to reduce being picked off by searchers.
- Pre‑trade scouting: send small “pings” and analyze cancel‑to‑fill and latency before committing large slices.
- Use relayer or protected execution channels for sensitive flows (e.g., arbitrage that could be frontrun).
Limitations, false positives and operational concerns
Measurement must be calibrated to avoid overreacting. Short windows can produce noisy ASR spikes during normal volatility. Use multi‑day baselines and instrument‑specific thresholds. Also, private data access is unequal: institutions with access to private relays and builder telemetry will have an edge. Even so, public mempool latency and on‑chain fills provide actionable signals for most market participants.
Where the market structure is heading
Sequencer decentralization efforts across major L2s, continued growth of builder marketplaces, and more institutional adoption of on‑chain quoting will alter toxicity dynamics. Two trends matter for traders:
- More transparent sequencing mechanisms: if fair sequencing auctions and public builder competition become standard, mempool lead advantage declines, lowering baseline toxicity.
- Specialized protected order types: exchanges and DEXs will increasingly offer maker‑protection primitives to attract professional liquidity, making venue selection a core execution decision for LPs and traders.
Checklist to implement this week
- Ingest fills, cancellations and mempool timestamps into a time‑series store for your top 5 traded instruments.
- Compute ASR (T=5s, X=0.1%) and realized spread on rolling 1h/24h windows.
- Set alert thresholds: ASR > 15% or realized spread 0 for 24h triggers defensive mode (widen spreads, reduce size).
- Test defensive tactics (post‑only orders, smaller slices) in a forked environment or during low capital exposure before applying live.
Orderflow toxicity is measurable and manageable. The right combination of mempool monitoring, sequencer awareness and disciplined, metric‑driven quoting policy will separate profitable market makers and savvy execution teams from those consistently picked off by faster, better‑informed searchers.